- Crésus Casino is closed since September 2024 per the ANJ annual report; any site claiming to be its support or successor should be treated with caution.
- Separate three different problems: a failed deposit, an approved-but-unpaid withdrawal, and a blocked account; each needs different evidence.
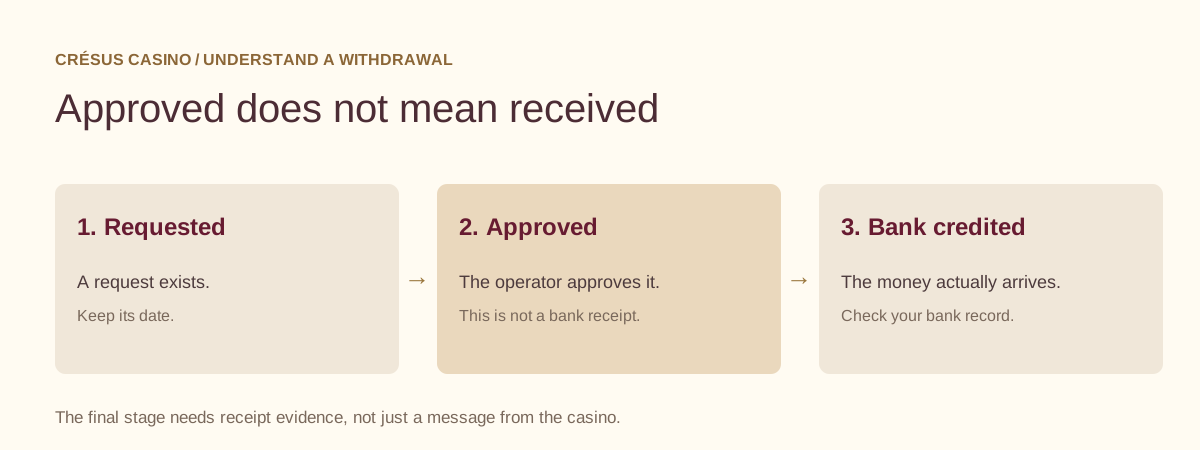
- Approved by the casino is not the same as credited by your bank; keep request, approval and receipt dates apart.
- Never pay a new deposit, fee or 'verification charge' to unlock old funds; that pattern is a classic recovery scam.
- Our site collects no documents and mediates no refunds; your bank and official French channels are the real routes.
Why the cashier no longer answers: the 2024 closure timeline
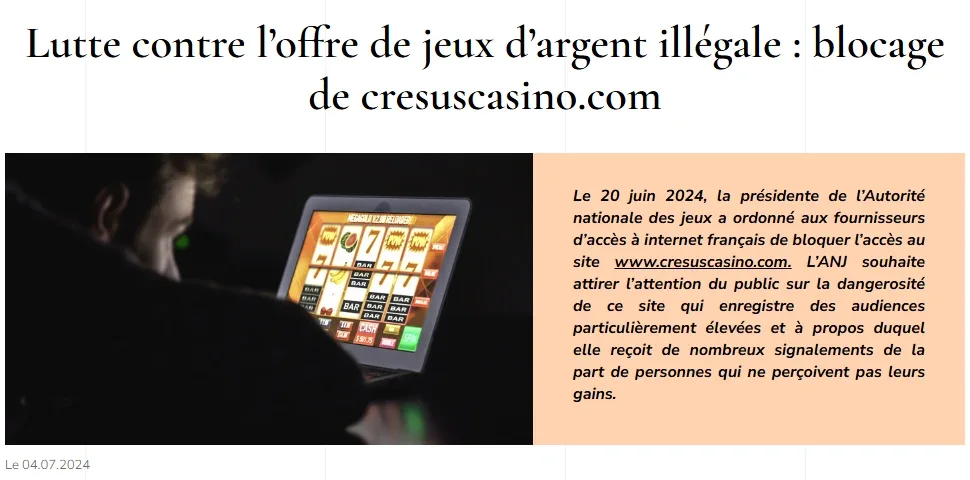
Before reconstructing your own case, anchor it in the verified chronology. On 20 June 2024 the French gambling regulator ANJ obtained a blocking order against cresuscasino.com, and on 4 July 2024 it publicly announced the measure, mentioning mirror sites and non-payment complaints. The ANJ annual report for 2024 records the permanent closure of the brand from September 2024. That means any balance, pending withdrawal or unanswered ticket from that period now sits with an operator that no longer runs a French-facing service.
This page is an independent editorial guide. We are not the old operator, we host no login form, and we never ask for passports, ID or banking documents. If you simply want to see clearly labelled current partner offers instead, they sit separately at our play page; the rest of this article is about documenting old money, not depositing new money.
How the 2024 closure unfolded · Clearly labelled partner offers
Failed deposit, unpaid withdrawal or blocked account: pick your scenario first
Forum history around Crésus shows three scenarios that people constantly mix up, and each demands different proof. Scenario one is the failed deposit: in a July 2022 thread relayed by user Ginie for Karine, two card deposits reportedly failed, and the moderator's first question was whether the bank had actually settled the debit. A failed authorisation that never settled is a banking matter, not a casino debt. Scenario two is the unpaid withdrawal: in January 2023 user Fj2 reported a €50 withdrawal still pending after five working days, and in April 2024 user Choupet described a request approved on 15 April that had still not arrived by 20 April. Scenario three is the blocked account: an October 2022 thread relayed for Romero concerned an account locked with a claimed €4,000 inside, where the cause was never established in the thread.
None of these threads contains verified bank proof of the final outcome, so treat them as illustrations of structure, not as statistics. The practical lesson is that your first task is classification. Write one sentence describing your case in the form: 'On [date] I [deposited / requested withdrawal of €X / lost access], the casino side showed [status], and my bank statement shows [settled / not settled / credited / not credited].' That single sentence determines which evidence matters and which organisation can actually act.
A blocked individual account is also different from the closure of the whole operator. If your account was locked in 2022 while the site still ran, your dispute was with the operator's terms process; if your withdrawal was pending in mid-2024, it collided with the blocking order and closure. The remedy path, and realistically the chance of recovery, differs between those situations, and nobody can honestly promise you an outcome in either.
Login problems versus brand closure · Reader reports and timelines
Request date, approval date, bank credit: three dates you must separate
The most common documentation error is treating 'withdrawal approved' as 'money received'. In the April 2024 Choupet thread, the request was approved on 15 April, the player still expected funds on 18 April, support suggested waiting until 26 April, and on 20 April nothing had arrived. Approval is an internal operator decision; the bank credit is a separate event days later, and only the second one is money in your hands.
Hypothetical worked example, labelled as such: imagine you requested €300 on Monday 3 June 2024, the account showed 'validated' on Wednesday 5 June, and your statement shows no incoming credit by Friday 14 June. Counting working days from approval, that is seven working days of silence after validation, but eleven calendar days from the original request. When you write to your bank or a consumer body, quote all three dates separately: request 03/06, approval 05/06, no credit as of 14/06. Mixing them lets the other side dismiss your complaint as premature or miscalculated.
Apply the same discipline to deposits. A card payment can show as 'pending' or 'authorised' without ever settling; only a settled debit is money that left your account. In the 2021 thread from user CresusFail, the author reported a debit that was never credited to the casino balance and a wait of around three months, with no confirmed refund visible in the discussion. If your statement line still says 'pending', ask your bank whether it will expire automatically; if it says settled, you have a documented transfer to trace.
| Status label | What it actually means | Evidence to keep |
|---|---|---|
| Requested | You submitted the cashout; nothing approved yet | Screenshot or email with request date and amount |
| Approved / validated | Operator agreed internally to pay | Approval email, account history entry |
| Sent / processed | Operator claims the transfer left | Transaction reference if provided |
| Bank credited | Money actually arrived; only this is received | Bank statement line with date and amount |
| Card authorisation (pending) | Bank reserved funds; may expire unused | Statement showing pending status |
| Settled debit | Money definitively left your account | Statement line plus merchant reference |
Looking for another offer?
Explore partner offers and check availability, terms and status. This is separate from any steps concerning an old Crésus balance.
Explore partner offers ↗The evidence file: what to gather before contacting anyone
Build a single folder, stored locally on your own device, before you write any complaint. The goal is that a bank adviser or consumer-body officer can reconstruct your case in five minutes without asking you follow-up questions. Do not upload this material to any website claiming to 'recover' Crésus funds, including ours: we receive editorial reports only through the contact page and never request financial documents.
For a failed deposit, the core items are the bank statement line showing the settled debit with its merchant reference, the casino cashier screenshot showing the deposit as failed or absent, and any support ticket acknowledging the incident. For an unpaid withdrawal, keep the withdrawal request confirmation, the approval message, the full account transaction history export if you still have access, and the bank statement covering the expected arrival window showing no matching credit. For a blocked account, preserve the last successful login date, the lockout message, your balance at that moment as shown in the account, and every email exchanged with support.
Add a one-page chronology at the front of the folder: a dated list of events in plain language, each line tied to a document. Hypothetical example: '15/06/2021 – card debit €200 settled (statement p.3); 15/06/2021 – casino balance unchanged (screenshot A); 20/06/2021 – ticket #48211 opened; 12/09/2021 – no refund received.' Banks and official services respond far better to this format than to a long emotional narrative, and it protects you if your own memory of dates fades.
- Export or photograph your casino transaction history and balance while any access remains.
- Download bank statements covering the deposit or expected withdrawal window as PDF.
- Save every support email and ticket number as files, not just in your inbox.
- Write the one-page dated chronology linking each event to a document.
- Store two copies locally; send nothing to unofficial 'recovery' services.
A complaint message that banks and officials can act on
Whether you write to your bank, a consumer association or a public body, the same skeleton works. Paragraph one: identity and facts — your name, the site (cresuscasino.com), the dates, the amounts, and the payment method. Paragraph two: the precise failure — 'deposit settled by my bank but never credited by the operator', or 'withdrawal approved on [date] but no credit received by [date]'. Paragraph three: what you have already done — tickets opened, replies received or silence. Paragraph four: the concrete request — a trace of the transfer, a written explanation, or the appropriate dispute procedure under your bank's own rules.
Keep the tone factual and attach the chronology plus the three or four decisive documents rather than the whole folder. Avoid accusations you cannot document; phrases like 'fraudulent site' are weaker than 'settled debit of €200 on 15/06/2021, merchant reference X, never credited, no refund as of today'. If French is not the recipient's working language, a short English version of the chronology is acceptable for your own bank, but official French bodies will generally expect French.
One firm rule: no legitimate process requires you to deposit more money to release old money. Any message claiming your withdrawal is 'blocked pending a verification deposit', a 'tax payment' or an 'account reactivation fee' is a recovery scam pattern, whoever it claims to be. The same caution applies to anyone offering to bypass the ANJ blocking order or geo-restrictions; this guide provides no such scheme, and following one would put your evidence and possibly your legal position at risk.
Where to take the file: bank first, then official French channels
Your bank is the first realistic stop because it alone can see the payment rails. Bring the chronology and ask two concrete questions: whether a given debit settled or can still be reversed under the bank's own procedures, and whether an expected incoming transfer can be traced. Deadlines, chargeback conditions and success odds depend on your card contract, your bank and the age of the transaction, so ask for your individual situation rather than relying on forum numbers; we deliberately do not quote invented time limits here.
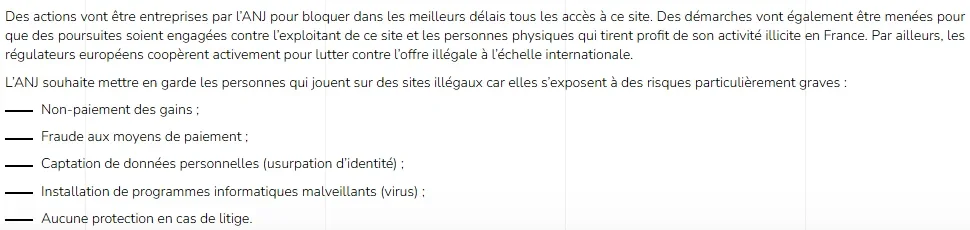
“Non-payment of winnings; payment fraud; capture of personal data.”
English translation of three items in the ANJ warning.
On the regulatory side, the ANJ is the authority that obtained the blocking order concerning cresuscasino.com and publishes the legal-framework position: online casino games such as slots and roulette are not authorised in France, and a foreign licence is not French permission. The ANJ's pages on illegal gambling and its announcement of the Crésus blocking are the verified sources to cite in your file. A prosecutor document dated 10 October 2025 is indexed publicly, but the full text is currently inaccessible to us, so we omit any detail about charges, names or judicial outcomes rather than guess.
For consumer disputes, French consumer-protection services and, where relevant, legal counsel can assess individual options; that assessment has to be individual because it depends on your contract, sums and dates. What no route can do is guarantee recovery from a closed, unauthorised operator — be suspicious of anyone who promises otherwise, especially for an upfront fee. If you self-excluded from gambling in the past, do not treat this process as a reason to open new gambling accounts; recovering old funds and playing again are separate decisions.
Recovery scams, fake successors and stale forum advice
Closure news attracts impersonators. Typical patterns seen around closed brands generally include lookalike domains claiming to be the 'new official Crésus', direct messages offering account recovery for a fee, and 'support agents' asking for ID photos or card photos by email. None of these can pay you: the original operator is closed, and we do not verify any current successor, mirror or working application, so treat every such claim as unproven until an official source confirms it.
How we check alternatives with dates · ANJ: which games are legal in France
Frequently asked questions
Can I still withdraw money from my old Crésus Casino account?
The brand was blocked in France on 20 June 2024 and closed permanently from September 2024, so there is no functioning cashier. Your realistic routes are your bank for settled payments and official French channels for complaints; no outcome can be guaranteed.
My withdrawal was approved but never arrived. What proves that?
Keep the request confirmation, the approval message with its date, and a bank statement covering the expected arrival window showing no matching credit. Approved by the operator and credited by your bank are separate events, so quote both dates distinctly.
My card was charged but the deposit never appeared. Is that the same as an unpaid withdrawal?
No. First check whether the debit actually settled or is only a pending authorisation that may expire. A settled debit never credited is a documented transfer your bank can trace; a failed authorisation is usually a banking matter only.
Someone contacted me offering to recover my Crésus balance for a fee. Should I pay?
No. Requests for upfront fees, 'verification deposits' or ID and card photos from unofficial contacts match recovery-scam patterns. We mediate no refunds and collect no documents; use your bank and official services directly.
Is there an official successor or new Crésus site where my balance moved?
Is online casino play even legal for me in France?
According to the ANJ, online casino games such as slots and roulette are not authorised in France, and a foreign licence does not constitute French permission. Check the ANJ's legal-offer pages for the current framework.